
Navigating New York’s auto insurance requirements can feel overwhelming, especially on Long Island where traffic patterns and local road conditions create unique coverage needs. Getting the right Long Island auto insurance policy protects you legally and financially, but finding affordable coverage takes strategy.
We at JW Hirschfeld Agency, Inc. help drivers cut through the confusion by connecting you with multiple carriers and personalized guidance. This guide walks you through what coverage you need, how to lower your costs, and why working with a local independent agent makes all the difference.
What New York Requires for Auto Insurance
Liability Coverage Minimums and Legal Requirements
New York mandates specific liability coverage minimums that every driver must carry. You need at least 25/50/25 coverage, which means 25,000 dollars in bodily injury liability per person, 50,000 dollars per accident, and 25,000 dollars in property damage liability. These aren’t suggestions-they’re legal requirements enforced by the state. If you’re caught driving without these minimums, New York imposes fines starting at 1,500 dollars for a first offense, plus potential license suspension and surcharges that can last three years.
Liability claims on Long Island frequently exceed these minimums, especially in high-density areas where multi-vehicle accidents happen regularly. Traffic density here creates genuine exposure beyond state minimums. We recommend higher limits like 100/300/100 for Long Island drivers because your actual costs in a serious accident could far outpace the legal minimum.
Personal Injury Protection Coverage
New York also requires Personal Injury Protection coverage, commonly called no-fault insurance, with a minimum of 50,000 dollars. This covers your medical expenses, lost wages, and essential services regardless of who caused an accident. Many Long Island drivers overlook this, assuming their health insurance covers accident-related injuries, but PIP fills gaps that standard health plans won’t.
Your health insurance may exclude accident-related treatment or impose high deductibles. PIP steps in to cover those costs without waiting for fault determination. This protection matters significantly on Long Island, where accident frequency remains high.
Uninsured and Underinsured Motorist Protection
Uninsured and underinsured motorist protection is equally important on Long Island. This coverage protects you when an at-fault driver lacks adequate insurance or flees the scene. We recommend matching your uninsured motorist limits to your liability limits so your protection remains consistent.
A local independent agent can explain how these requirements interact and identify which coverage combinations make sense for your specific situation, rather than just meeting the bare legal minimum. Understanding these layers of protection positions you to explore practical strategies for lowering your overall costs.
How Long Island Drivers Can Lower Their Auto Insurance Costs
Bundle Home and Auto Policies for Maximum Savings
Bundling your home and auto policies with the same carrier typically saves 15 to 25 percent on your combined premiums. Insurers reward customer loyalty and reduce their administrative costs when they manage multiple policies. However, bundling only helps if you compare multiple carriers first. Many drivers bundle with their current insurer without checking whether competitors offer better bundled rates. Shopping with an independent agency lets you see whether bundling with one company beats shopping separately with another, ensuring you capture the full savings available to you.
Maintain a Clean Driving Record and Ask About Safe Driver Discounts
Your driving record directly impacts your rates, and this matters more on Long Island than most regions because insurance companies weight accident frequency heavily in this area. A clean driving record for three to five years qualifies you for safe driver discounts ranging from 10 to 30 percent depending on your insurer. One accident or traffic violation increases your premium by 20 to 40 percent for three years. If you have a violation on your record, some insurers offer defensive driving course discounts that reduce premiums by 5 to 10 percent and sometimes remove points from your driving record.
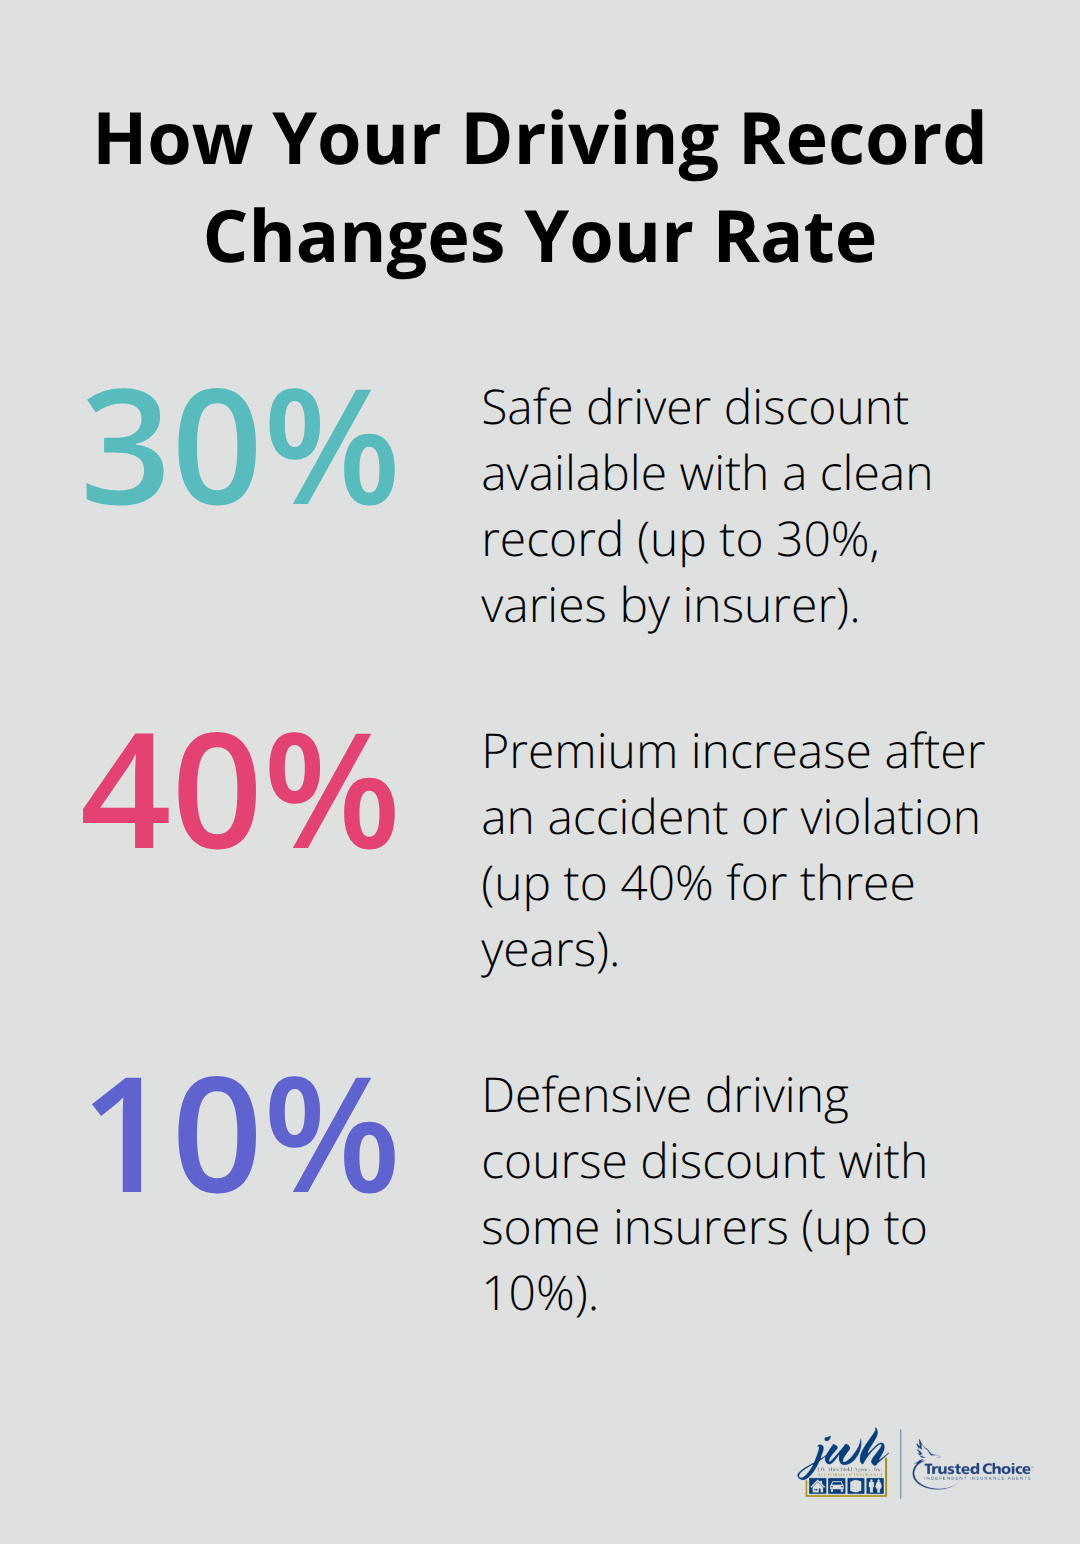
Taking a defensive driving course costs 20 to 50 dollars but pays for itself within the first year through premium reductions.
Shop Around with Multiple Carriers Through an Independent Agent
Most Long Island drivers stick with their current insurer for years without comparing quotes, yet shopping around with multiple carriers is non-negotiable. An independent insurance agency represents multiple different carriers, allowing you to see side-by-side comparisons in one conversation rather than contacting each company individually. This approach saves time and reveals which carriers offer the best rates for your specific profile. Some carriers specialize in insuring drivers with accidents or violations, while others focus on clean-record drivers with lower risk profiles. Rate differences between carriers for identical coverage can exceed 500 dollars annually on Long Island.
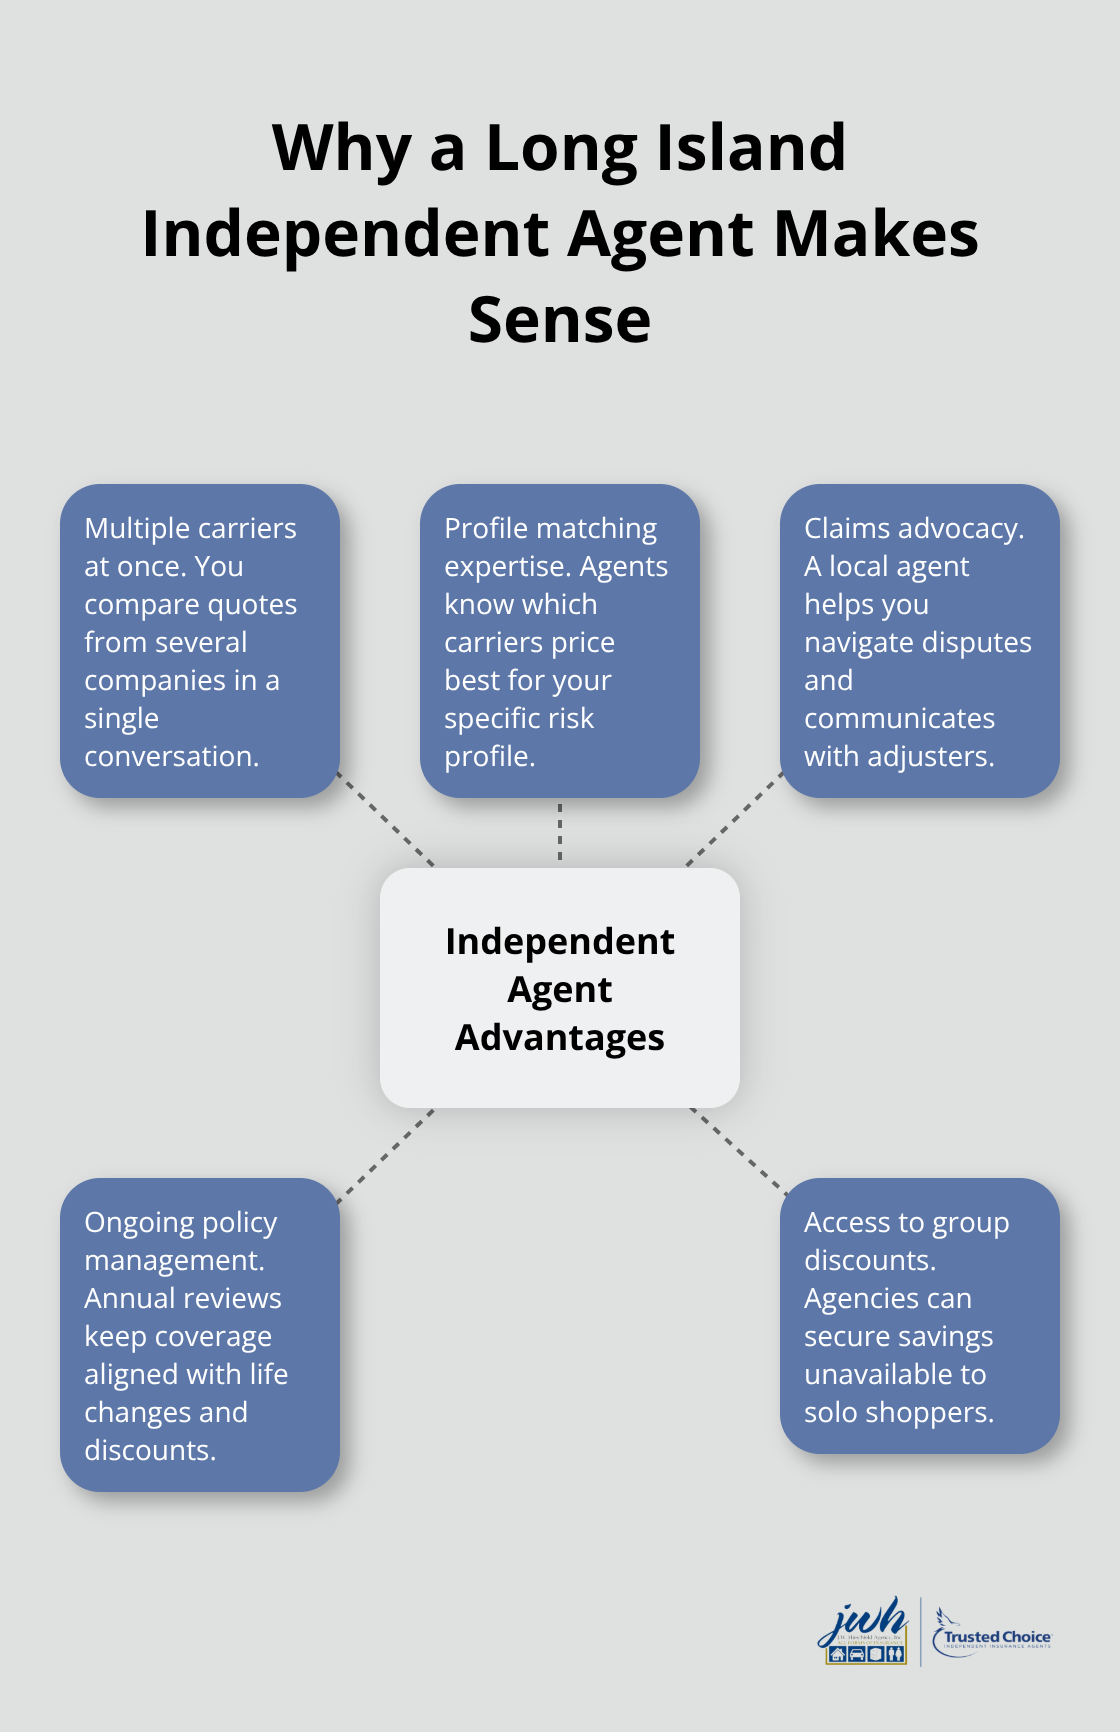
Your age, zip code, vehicle type, and coverage choices all influence which carriers price most competitively for you. An independent agent asks detailed questions about your driving habits, vehicle use, and coverage needs, then matches you with carriers that price favorably for your situation. Direct online quotes often miss discounts because algorithms cannot account for the full range of factors that affect your rate. Independent agents also access group discounts unavailable to individual shoppers. Understanding your options positions you to make informed decisions about coverage that protects your finances while keeping premiums manageable-and that’s where working with a local independent agent becomes invaluable.
Why Independent Agents Beat Shopping Alone
Multiple Carriers, One Conversation
Comparing auto insurance rates across multiple carriers takes hours when you contact each company individually, yet most Long Island drivers never do it. An independent insurance agency represents dozens of carriers simultaneously, meaning you see competitive quotes from different companies in a single conversation rather than spending your evening on hold with customer service representatives. JW Hirschfeld Agency, Inc. works with multiple top carriers, so you access pricing options that online quote tools simply cannot show you. Rate differences between carriers for identical coverage routinely exceed 500 dollars annually on Long Island, making this comparison genuinely worthwhile.
Matching Your Profile to the Right Carrier
Independent agents know which carriers offer the best rates for specific driver profiles. A carrier offering rock-bottom rates for drivers with clean records might charge significantly more for someone with an accident history, while another specializes in exactly that market segment. Direct online shopping misses these nuances entirely because algorithms cannot replicate the judgment an agent applies when matching your profile to carriers most likely to price competitively for your situation. An agent asks detailed questions about your driving habits, vehicle use, and coverage needs, then identifies which carriers price most favorably for you.
Claims Advocacy and Local Knowledge
An independent agent provides something insurance companies and online platforms cannot: hands-on advocacy during claims. When you file a claim, you deal directly with your agent rather than navigating a phone tree at a distant claims center. Long Island drivers know that local expertise matters when accidents happen in high-traffic areas where liability disputes frequently arise. An agent who understands Long Island road conditions, common accident patterns, and local repair shops communicates more effectively with adjusters on your behalf.
Ongoing Policy Management
Your agent reviews your policy annually to confirm your coverage keeps pace with your life changes, catches discounts you qualify for but never knew existed, and handles policy adjustments without making you navigate complex forms alone. This ongoing relationship prevents costly coverage gaps and maintains the right protection without overpaying for unnecessary add-ons. Independent agents (unlike large insurers with rotating customer service representatives) maintain continuity in your account, meaning the same person handles your questions year after year.
Final Thoughts
New York’s auto insurance requirements protect you and other drivers on the road, and Long Island’s traffic patterns make higher coverage limits worthwhile beyond the legal minimums. You need liability coverage at minimum 25/50/25, personal injury protection of at least 50,000 dollars, and uninsured motorist protection to cover gaps when other drivers lack adequate insurance. These legal minimums form your foundation, but Long Island’s accident frequency means most drivers benefit from stronger protection.
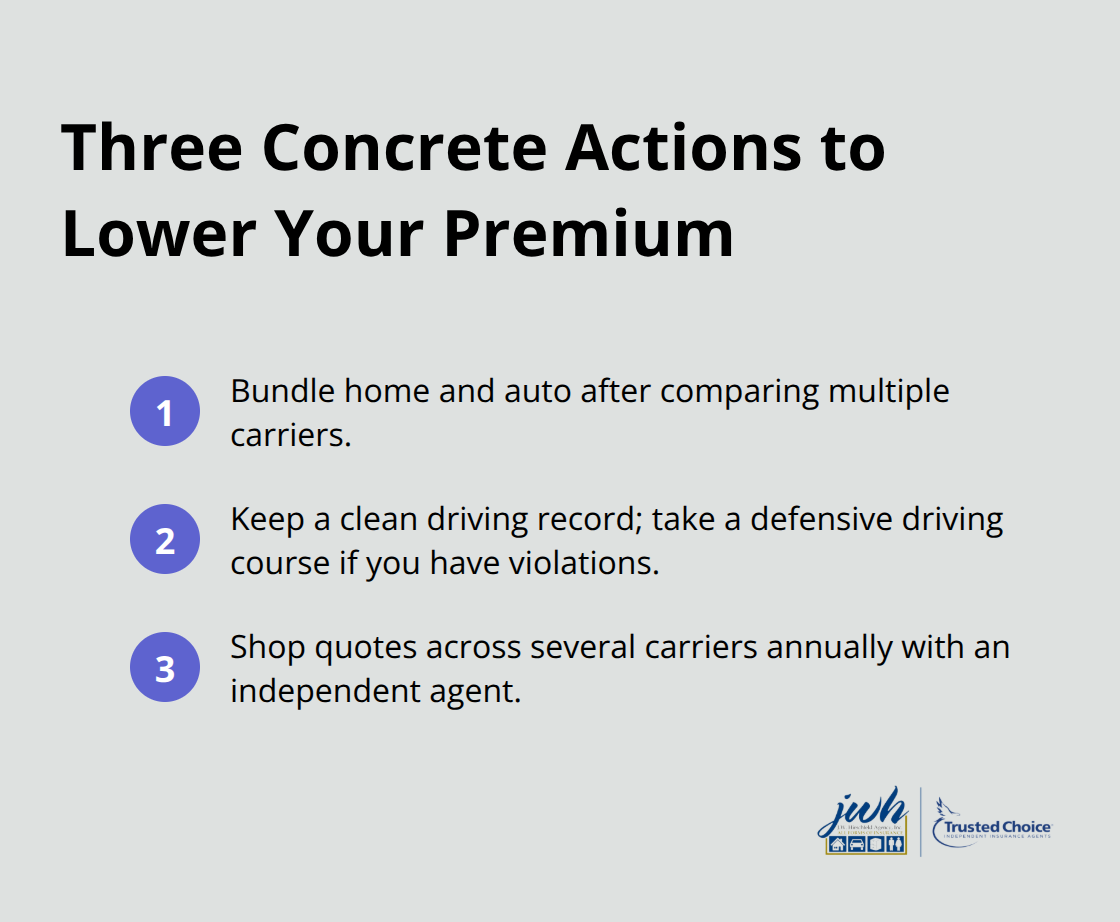
Lowering your Long Island auto insurance policy costs requires three concrete actions. First, bundle your home and auto policies to capture 15 to 25 percent savings, but only after comparing rates across multiple carriers. Second, maintain a clean driving record to qualify for safe driver discounts ranging from 10 to 30 percent, and consider a defensive driving course if violations appear on your record. Third, shop around with multiple carriers rather than renewing with your current insurer year after year, since rate differences between carriers for identical coverage frequently exceed 500 dollars annually.
Working with a local independent agent transforms this process from time-consuming to straightforward. An independent agency represents multiple top carriers, eliminates the need to contact each company individually, and matches your specific profile to carriers most likely to price competitively for you. Your agent accesses group discounts unavailable to individual shoppers, provides hands-on advocacy when claims arise, and handles your account year after year while catching new discounts and adjusting coverage as your life changes. Contact JW Hirschfeld Agency, Inc. to discuss your coverage needs and see how working with an independent agent saves you money while protecting your finances.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.