
Rental property owners in Huntington face real financial exposure when coverage falls short. Most landlords don’t realize how many gaps exist in standard policies until a tenant injury or vacancy hits their cash flow.
We at JW Hirschfeld Agency, Inc. work with property owners every day to build rental property insurance plans that actually protect their investments. The right coverage strategy makes the difference between a manageable claim and a financial crisis.
What Coverage Do Rental Property Owners Actually Need
Rental property insurance differs fundamentally from homeowners insurance because it protects a business asset, not a personal residence. Homeowners policies cover owner-occupied dwellings and personal liability, but they explicitly exclude rental income and tenant-related exposures. When you rent out a property, you need specific protections that address the unique risks landlords face.
The Foundation: Dwelling and Liability Coverage
Dwelling coverage protects the physical structure itself-walls, roof, foundation, and permanent fixtures-against perils like fire, wind, and theft. This forms your baseline, but it cannot stand alone. Liability coverage shields you when a tenant or visitor gets injured on your property and sues for medical bills or damages. Without adequate liability limits, a single slip-and-fall incident can wipe out years of rental income. Loss of rent coverage compensates you during involuntary vacancies caused by covered perils, ensuring your mortgage and expenses don’t drain your reserves while the property sits empty or undergoes repairs.
Why Basic Coverage Falls Short
Many Huntington landlords stop at basic dwelling and liability, missing critical gaps that expose them to serious financial loss. Property damage liability covers damage you cause to a tenant’s belongings, while loss assessment coverage protects you if the property is part of a condo association facing special assessments. Water damage and mold coverage requires careful attention because standard policies often exclude or severely limit these claims, yet they rank among the costliest landlord losses.
Additional Protections That Matter
Vandalism and malicious mischief coverage matters more than most landlords think, especially in areas with frequent tenant turnover. Loss of rents extension typically covers up to 12 months of income during extended vacancy periods-a protection that many policies limit to just 30 days. Equipment breakdown coverage protects heating, cooling, and electrical systems that tenants depend on, and landlord’s furnishings coverage applies if you provide appliances or furniture in the rental unit.
The National Association of Realtors reports that rental property owners face an average of 23 days of vacancy annually, translating to roughly 6% of potential annual income lost. Without loss of rent protection, that income gap comes directly from your pocket. These gaps between what you think you’re covered for and what your policy actually pays can transform a manageable situation into a financial emergency-which is exactly why working with an independent agent who understands Huntington’s rental market makes such a difference.
Why Independent Agents Deliver Better Rental Coverage
Multiple Carriers Mean Real Savings
When you call a captive insurance company, an agent sells only that one company’s policies. That agent cannot offer alternatives if that carrier’s rental property coverage doesn’t fit your Huntington investment. Independent agents work differently. We at JW Hirschfeld Agency, Inc. represent multiple top carriers, which means we can compare dwelling limits, liability caps, loss of rent terms, and pricing across different companies to find what actually works for your specific properties.
This access to multiple carriers directly impacts your wallet. When you work with a captive agent, you never see those savings because you cannot compare options. Independent brokers show you what each carrier charges for the same dwelling limits and liability protection, then you decide based on real numbers rather than assumption.
Customized Policies for Your Properties
A landlord with three single-family homes needs a different approach than one managing a duplex with shared systems, yet many agents force the same template onto every client. We build policies around your actual exposures, not around what one carrier happens to offer. We also layer in bundle discounts that independent brokers can match. If you insure your primary residence, vehicles, and rental properties with us, you access multi-policy discounts that reduce your overall insurance costs significantly.
Local Knowledge That Protects Your Investment
The rental market in Huntington moves fast, and coverage needs shift when tenants turn over, property values increase, or you add amenities that change risk profiles. A local independent agent understands these dynamics because we work within this community every day. We know which neighborhoods experience higher vacancy rates, where tenant turnover peaks seasonally, and how local building codes affect replacement costs.
When a claim happens, we advocate for you from day one instead of simply processing paperwork. We file claims on your behalf, push back on low settlements, and make sure your carrier honors what you paid for. That hands-on relationship during a crisis separates independent brokers from agents at large corporate offices who handle hundreds of claims impersonally.
Proactive Coverage Adjustments
We stay current on coverage changes and emerging exposures specific to Huntington properties. If new liability trends emerge around pool safety or parking lot incidents in our area, we contact clients to discuss whether additional coverage makes sense. This local accountability and ongoing relationship mean your rental property insurance stays aligned with your actual risks rather than becoming outdated. These gaps between what you think you’re covered for and what your policy actually pays can transform a manageable situation into a financial emergency-which is exactly why identifying and addressing coverage gaps matters before a loss occurs.
What Coverage Gaps Cost Huntington Landlords
Underinsuring Your Building Structure
Huntington rental property owners consistently underestimate the replacement cost of their structures, and this mistake hits hard when a major loss occurs. Most landlords base dwelling limits on what they paid for the property years ago, not accounting for construction inflation.
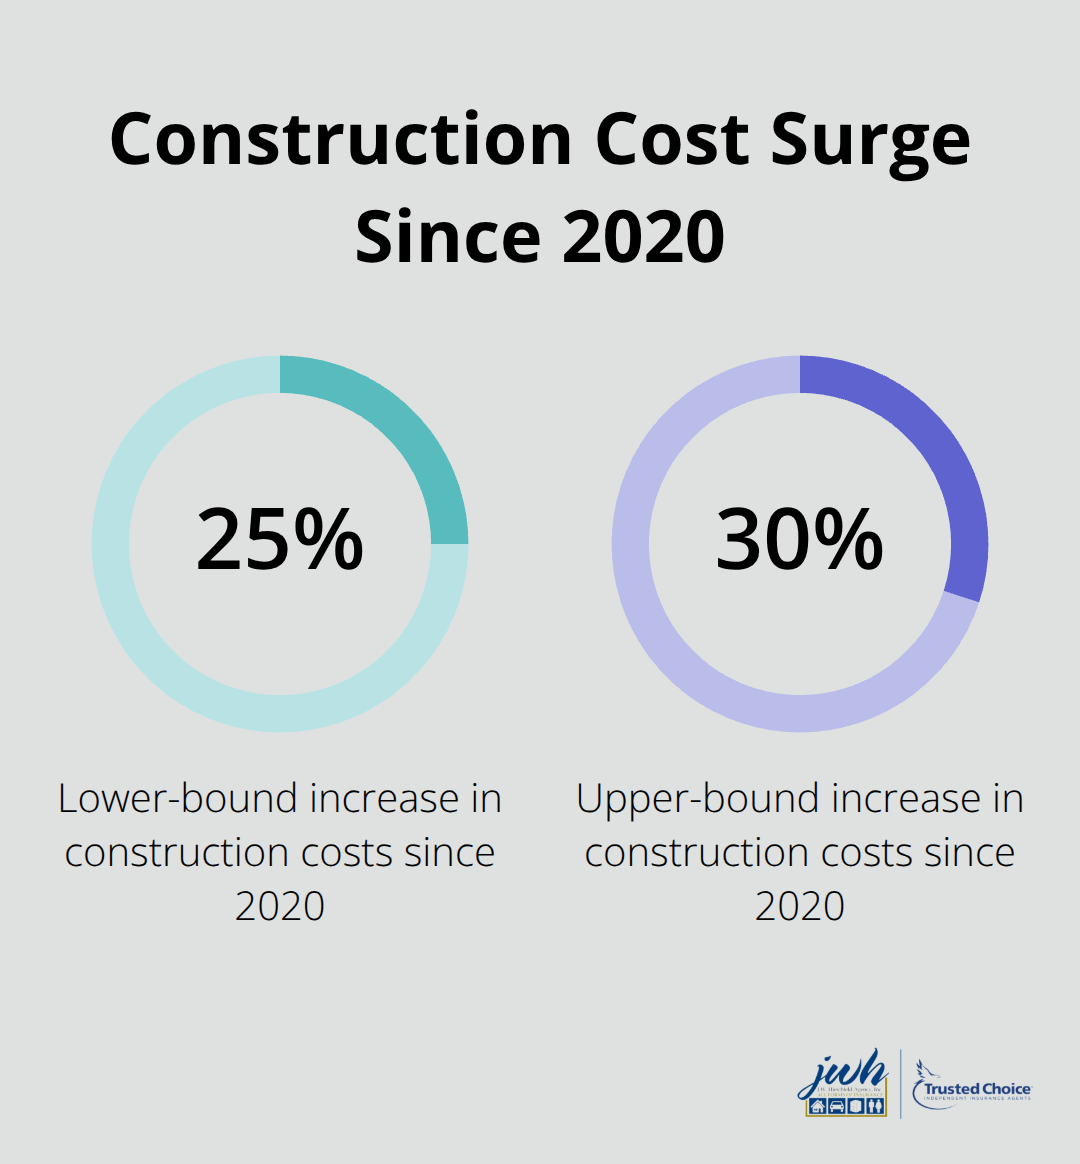
Since 2020, construction costs have risen roughly 25 to 30 percent, yet many policies still carry limits from 2018 or 2019. When fire or wind damage requires rebuilding, that gap between your coverage limit and actual reconstruction costs becomes your personal liability.
A two-bedroom home in Huntington that cost $350,000 to purchase may require $450,000 or more to rebuild today, depending on materials and labor. If your dwelling limit sits at $350,000, you absorb the $100,000+ difference yourself. This isn’t theoretical-the Insurance Information Institute reports that underinsurance claims represent a significant portion of disputed rental property claims annually. The fix requires an honest conversation about replacement value versus purchase price, and many agents skip this conversation entirely because it takes time.
Liability Gaps Leave You Exposed
Liability protection for tenant injuries represents the exposure that keeps most landlords awake at night, yet many carry limits that haven’t been reviewed in five years or more. A single slip-and-fall claim involving a tenant can easily exceed $100,000 in medical costs plus legal fees and settlement amounts. Standard rental policies often cap liability at $100,000 or $300,000, which sounds adequate until you face a serious injury case.
Huntington’s cost of living means medical expenses and jury awards trend higher than national averages, making baseline liability limits genuinely risky. A tenant who suffers a serious injury on your property can pursue damages that far exceed what your policy covers, leaving you personally responsible for the excess amount. This exposure grows when your property attracts multiple tenants or experiences high turnover, each interaction creating new liability scenarios.
Loss of Rent Coverage That Actually Covers
Loss of rental income during extended vacancies represents the third major gap, and this one catches landlords completely off guard. Standard policies typically cover only 30 days of lost rent following a covered peril, but major repairs often take 60, 90, or even 120 days. A roof replacement or significant water damage can leave your property uninhabitable for months while your mortgage, property taxes, and maintenance costs continue.
Extended vacancy periods from major damage claims create cash flow crises for landlords who haven’t extended their loss of rent coverage to match realistic repair timelines. Your policy should cover the full duration of repairs, not just an arbitrary 30-day window. Without this protection, you face months of negative cash flow while waiting for contractors to complete work and tenants to return.
Final Thoughts
Rental property insurance protects your Huntington investment only when coverage matches your real exposures. The gaps we’ve covered-underinsured structures, inadequate liability limits, and insufficient loss of rent protection-represent the difference between a manageable claim and financial devastation. Most landlords face these gaps too late, after a loss forces them to pay out of pocket for what they assumed was covered.
Working with a local independent agent changes this equation entirely. We at JW Hirschfeld Agency, Inc. represent multiple top carriers, which means we compare dwelling limits, liability caps, and loss of rent terms across different companies to find pricing and coverage that actually fit your properties. A captive agent cannot offer this comparison because they sell only one company’s policies, and that limitation costs you money while leaving coverage gaps unaddressed. When claims happen, we advocate for you from day one instead of simply processing paperwork, and we push back on low settlements to make sure your carrier honors what you paid for.
The rental market in Huntington moves fast, and coverage needs shift when property values increase, tenants turn over, or you add amenities that change risk profiles. Contact JW Hirschfeld Agency, Inc. to discuss your rental properties and receive a quote that reflects competitive pricing across multiple carriers. We’ll review your current coverage, identify gaps, and build a rental property insurance strategy tailored to your Huntington investment.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.