
Huntington homeowners face unique insurance challenges that generic policies often miss. Coastal storms, rising property values, and local claim patterns demand coverage tailored to your area.
We at JW Hirschfeld Agency, Inc. help homeowners in the Huntington area navigate these complexities with personalized guidance. This guide covers the risks you face, the coverage you need, and why local expertise matters.
What Huntington Homeowners Face: Local Risks That Shape Your Coverage
Coastal Weather Threats and Storm Damage
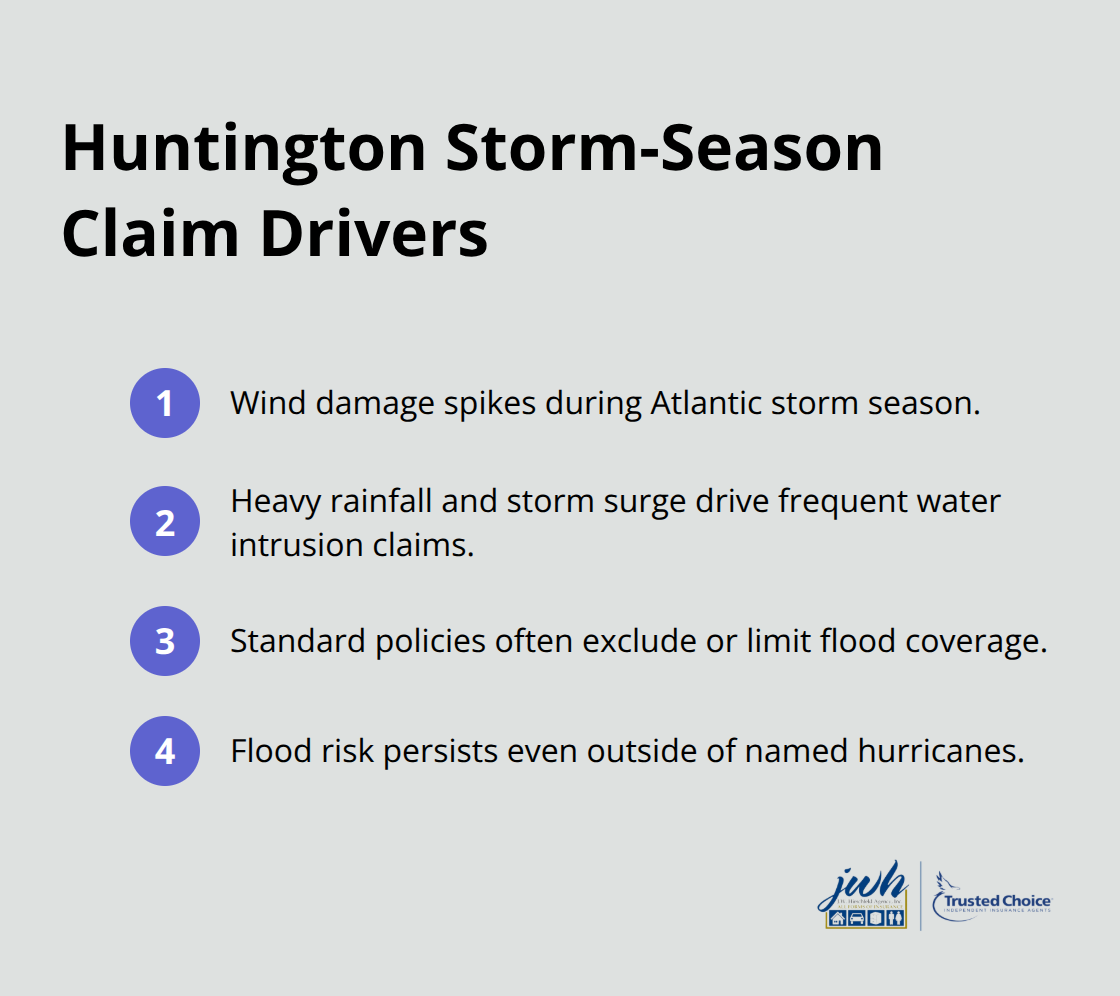
Huntington sits directly in the path of Atlantic hurricane season, and this geography shapes everything about your insurance needs. Between June and November, tropical storms and nor’easters regularly threaten the area, with hurricane-force winds capable of tearing roofs, shattering windows, and flooding basements. The National Hurricane Center data shows that Long Island experiences direct hurricane impacts roughly every 10 to 15 years, meaning most Huntington homeowners will face at least one major storm during their time in the area.
Wind damage claims spike dramatically during storm season, and water damage from storm surge and heavy rainfall ranks among the most frequent and costly claims filed in coastal Nassau County. Your standard homeowners policy covers wind damage, but many policies exclude or severely limit flood coverage-a critical gap since one in four insured homeowners file a flood claim during a 30-year mortgage period.
Understanding Replacement Costs in Today’s Market
Property values in Huntington have climbed steadily, with median home prices around $575,000 to $650,000 depending on proximity to the water and local schools. This matters directly to your insurance because replacement cost coverage must reflect what it actually costs to rebuild your home today, not what you paid for it years ago.
Many homeowners underestimate replacement costs by 15 to 25 percent, thinking their dwelling coverage limit is adequate when it falls short of current construction expenses. Labor costs and materials have increased substantially since the pandemic, and coastal properties face higher rebuilding expenses due to stricter building codes and specialized contractors. Try a professional home valuation or detailed cost estimate every three to five years rather than relying on outdated figures.
Common Claims in the Huntington Area
Common claims in Huntington include roof damage from wind and ice dams, water intrusion from aging foundations and coastal moisture, and liability claims from slip-and-fall accidents on icy driveways during harsh winters. Theft and burglary also appear regularly in the area, particularly in seasonal homes left vacant during winter months.
Understanding these patterns helps you identify coverage gaps and ensures your policy actually protects what matters most when something goes wrong. Separate flood insurance through the National Flood Insurance Program or private carriers often provides better coverage at competitive rates than the government program alone. As a third-generation, family-owned independent insurance agency in Huntington, we work with homeowners to evaluate whether additional flood protection makes sense for your specific property and risk profile.
Coverage Types Every Huntington Homeowner Needs
Your homeowners policy consists of several distinct coverage types, and understanding what each one protects-and what it leaves exposed-is the difference between adequate protection and a financial disaster when claims hit.
Dwelling Coverage and Structure Protection
Huntington homeowners need dwelling coverage to protect the structure itself, and this coverage should reflect the actual cost to rebuild your home with current materials and labor rates, not the market value. If your home would cost $450,000 to rebuild today but you only carry $350,000 in dwelling coverage, you absorb the gap out of pocket. The Insurance Information Institute reports that the average homeowners insurance claim runs around $11,000, but coastal properties in Nassau County regularly see claims exceeding $25,000 for roof damage alone.
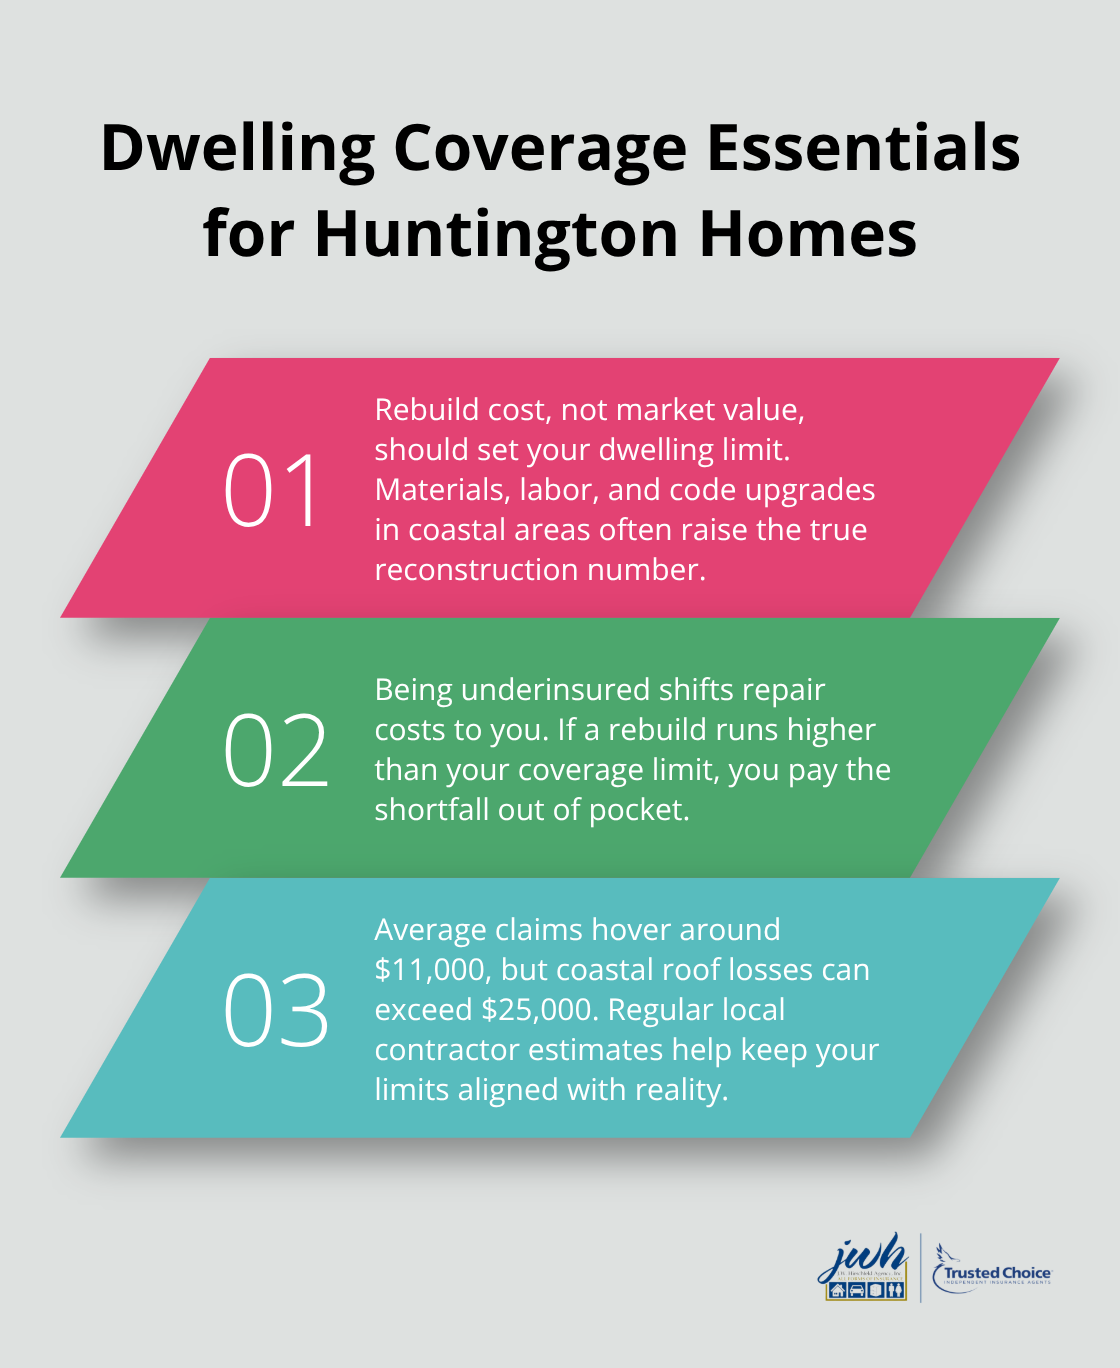
Many Huntington homeowners discover their dwelling limit is inadequate only after a claim, when adjusters reveal that the cost to repair far exceeds their coverage limit. Request a detailed replacement cost estimate from a local contractor every three to five years, not just a rough online calculator, since Huntington’s coastal location means specialized waterproofing, reinforced framing, and elevated construction add measurable costs compared to inland properties.
Personal Property and Contents Protection
Personal property coverage protects your belongings-furniture, electronics, clothing, and other contents-up to a percentage of your dwelling coverage, typically 50 to 70 percent. This matters because standard homeowners policies cap certain high-value items like jewelry, artwork, and collectibles at $1,500 to $2,500 total, which falls far short if you own meaningful pieces. Scheduled personal property endorsements extend coverage for these items at their actual value, protecting what matters most without arbitrary caps.
Liability Coverage for Accidents on Your Property
Liability coverage protects you financially if someone is injured on your property or if you damage someone else’s property, and it covers both legal defense costs and settlement amounts. Huntington’s winter conditions create genuine liability exposure: slip-and-fall accidents on icy driveways result in serious injuries, and your standard policy typically covers $100,000 to $300,000 in liability. An umbrella policy adds $1 million or more in additional liability protection for roughly $150 to $300 annually, a practical safeguard if you have significant assets to protect.
Why Coverage Limits Matter Year After Year
Your coverage limits should shift as your home and circumstances change. Home improvements, significant purchases, and rising construction costs all demand that you evaluate your policy annually, because gaps in coverage compound quickly when claims occur. As an independent agency representing multiple top carriers, we at JW Hirschfeld Agency, Inc. help homeowners find tailored coverage and competitive pricing that actually matches their Huntington property and risk profile.
Understanding your coverage types positions you to identify what protection you actually have in place. The next step involves working with an agent who knows Huntington’s specific risks and can match you with carriers that deliver both competitive rates and reliable claims support when you need it most.
Why Independent Agents Deliver Better Coverage for Huntington Homes
Multiple Carriers Mean Better Rates for Your Property
Huntington homeowners often assume that buying insurance directly from a major carrier or through an online aggregator saves money and simplifies the process. This assumption costs you money and leaves gaps in your protection. Independent insurance agents represent multiple carriers simultaneously, which means we can compare actual quotes from 10, 15, or even 20 different companies to find the coverage that matches your specific Huntington property and risk profile.
A homeowner with a coastal property, recent roof work, and a swimming pool faces entirely different underwriting than someone with an inland ranch home, yet most online platforms treat these situations identically. When you work with an independent agent, you receive customized quotes reflecting your actual risk factors rather than generic pricing algorithms. Huntington’s coastal location, aging housing stock in some neighborhoods, and seasonal weather patterns create local underwriting nuances that national carriers sometimes miss or overcharge for.
Direct insurers employ captive agents who sell only one company’s products, which means their recommendations are limited to whatever their employer offers, regardless of whether better options exist elsewhere. This structural limitation costs you thousands of dollars over time.
Local Expertise Shapes Your Coverage Strategy
We at JW Hirschfeld Agency, Inc. handle these complexities daily, knowing which carriers offer competitive rates for properties near the water and which ones price defensively due to storm exposure. Our nearly a century of local trust means we understand Huntington’s building codes, local contractor costs, and the specific underwriting preferences of each carrier we represent.
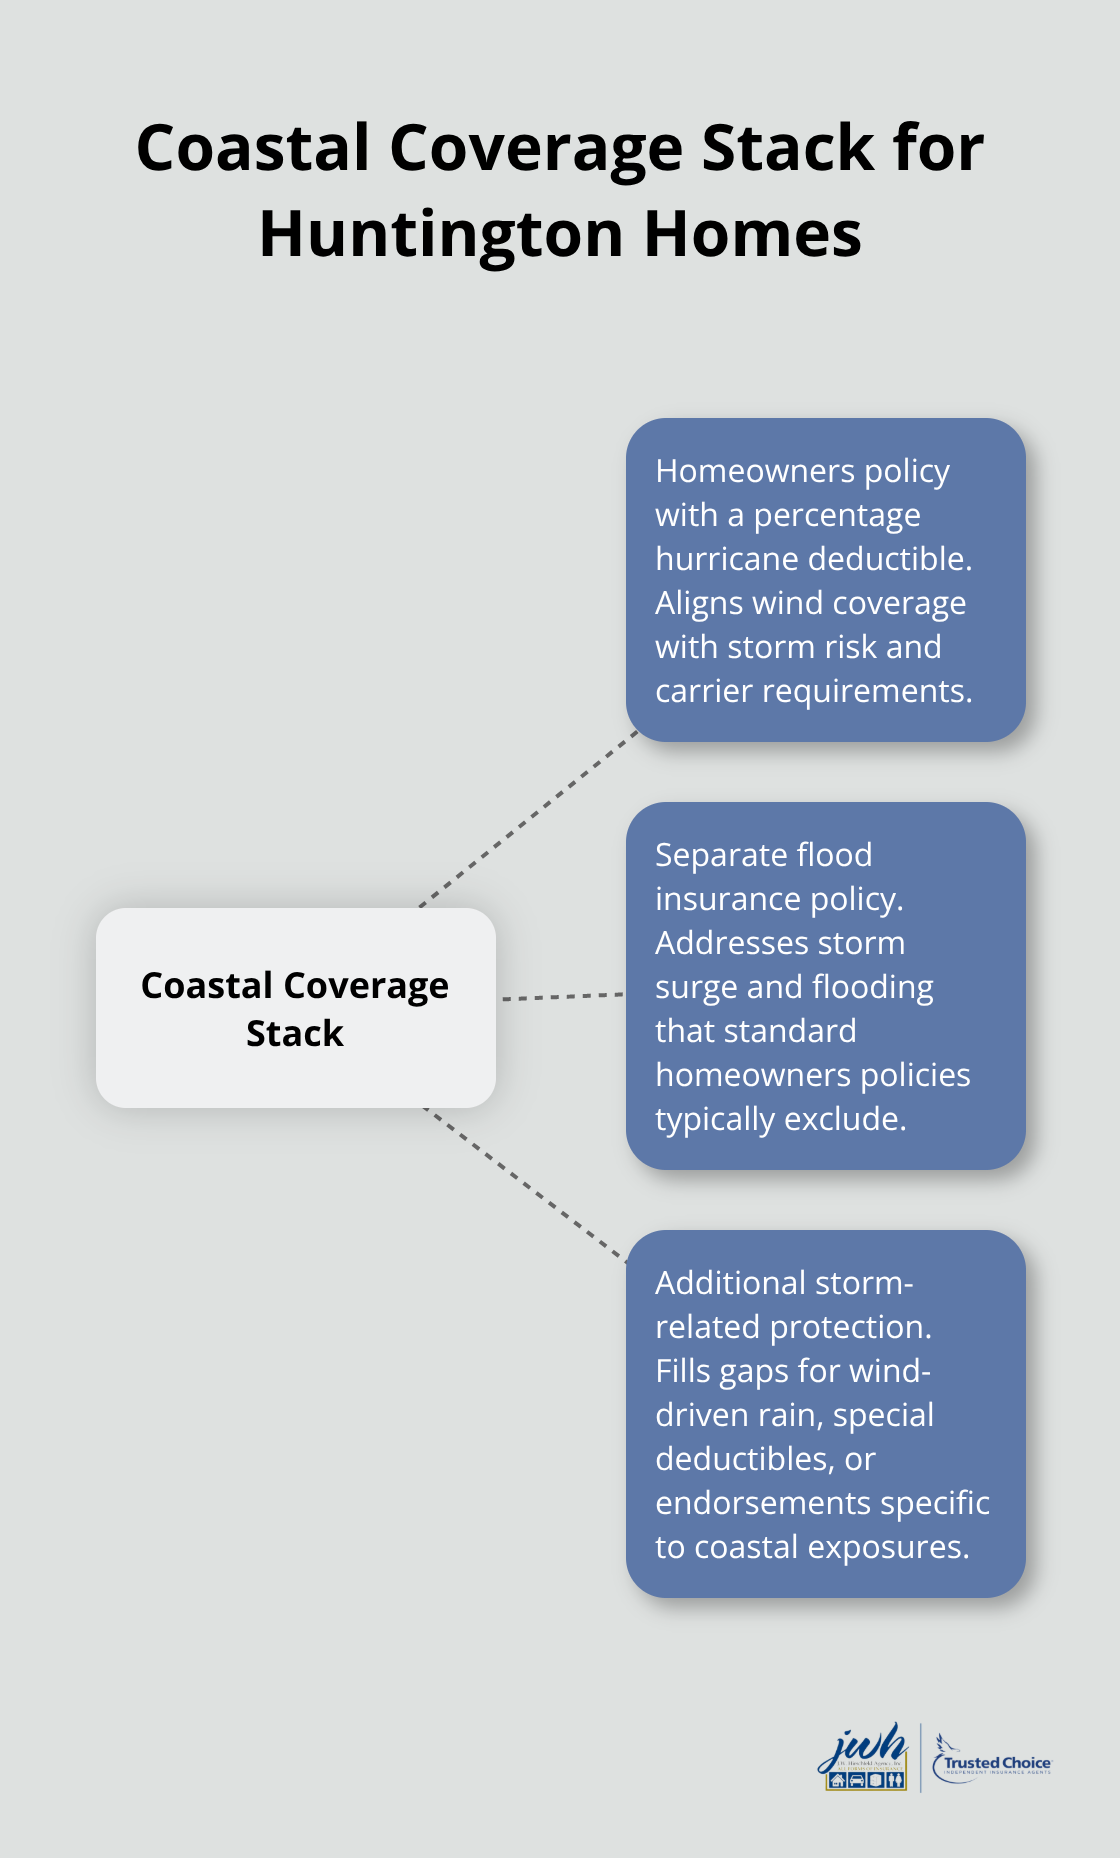
This local knowledge allows us to place your coverage strategically rather than accepting whatever the first company offers. Coastal Long Island homes generally need three coverages: a homeowners policy for wind (with a percentage hurricane deductible), a separate flood policy, and additional protection for storm-related damage. Your coverage reflects Huntington’s actual risks, not generic assumptions about Long Island properties.
Claims Support That Actually Works
Claims support separates independent agents from direct carriers, and this distinction becomes painfully obvious when you actually need to file a claim. Major carriers employ claims adjusters managing hundreds of files simultaneously, while independent agents work with you and the adjuster to ensure your claim receives proper attention and fair settlement.
When a nor’easter damages your roof or water intrusion affects your basement, having someone who knows your property and your coverage fighting on your behalf makes a measurable difference in claim outcomes. Independent agents also handle policy updates and coverage adjustments without forcing you through impersonal phone trees or website portals, because your account isn’t just a file number in a massive database.
Hands-On Advocacy Throughout Your Coverage
We provide bundle discounts and act as hands-on advocates through claims, backed by personalized service that national carriers simply cannot match. Your independent agent knows your home, your situation, and your coverage inside and out, which means faster resolution when problems arise and better protection against gaps you didn’t know existed.
Final Thoughts
Protecting your Huntington home requires coverage that reflects your specific property and actual coastal risks rather than generic policies that miss local complexities. Your dwelling coverage must match current reconstruction costs, your liability limits must protect your assets, and your flood insurance must address your property’s elevation and flood risk. Home insurance in the Huntington area works best when you evaluate these protections annually and adjust them as your home and circumstances change.
The practical next step involves reviewing your current policy against current reconstruction costs from local contractors and verifying that your liability limits match your actual asset exposure. Many homeowners discover coverage gaps during this review that cost thousands to address after claims occur, so comparing your dwelling limit against what it would actually cost to rebuild your home today matters far more than the price you paid years ago. Separate flood insurance through private carriers often provides better coverage at competitive rates than the government program alone, and umbrella policies extend liability protection beyond standard homeowners coverage for roughly $150 to $300 annually.
Working with JW Hirschfeld Agency, Inc. means accessing multiple carriers simultaneously rather than accepting whatever one company offers, backed by personalized service and nearly a century of local trust in Huntington. We represent top carriers, handle claims advocacy, and provide ongoing coverage adjustments without forcing you through impersonal systems, because your protection matters more than processing efficiency. Your Huntington home deserves coverage that actually matches your risks and your situation.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.