
Huntington homeowners often overpay for coverage they don’t need while missing gaps that leave them exposed. We at JW Hirschfeld Agency, Inc. see this pattern repeatedly, and it costs families thousands annually.
These Huntington home insurance tips focus on real savings strategies and the coverage mistakes that matter most. Working with a local independent agent gives you access to options online quotes simply can’t match.
How to Cut Your Huntington Home Insurance Costs
Bundle Your Policies for Maximum Savings
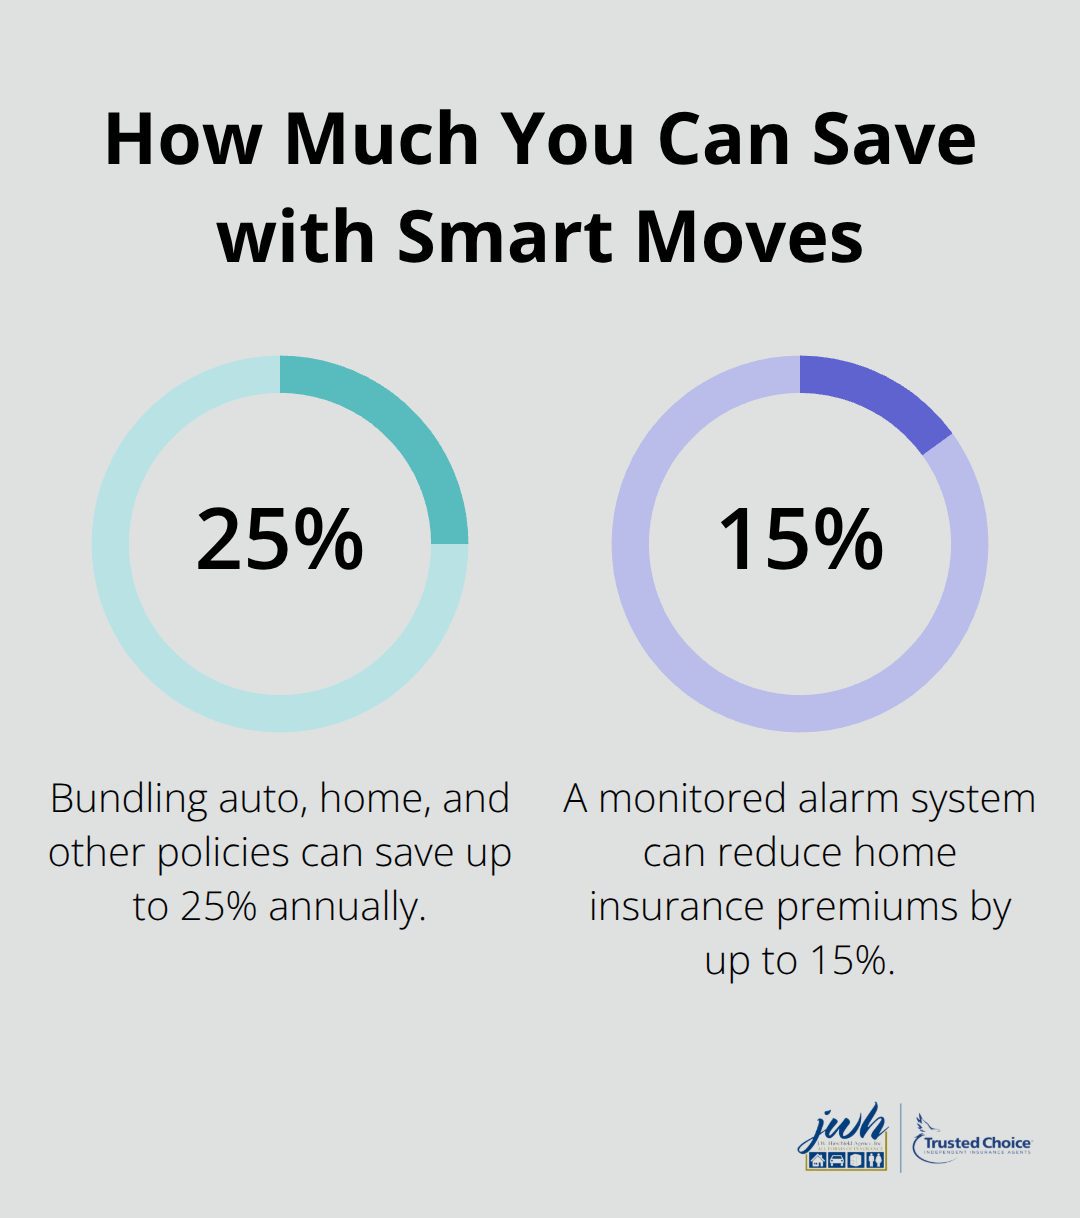
Bundling your auto, home, and other policies with one carrier typically saves between 15% and 25% on your annual premiums. Online quote tools lock you into a single insurer’s pricing, but independent agents represent multiple top carriers and can find the best bundle rates for your specific situation. The savings compound when you add watercraft or umbrella coverage to the mix, and you avoid juggling multiple bills and renewal dates.
Invest in Home Security Features
Security upgrades directly impact what you pay each year. A monitored alarm system can reduce your home insurance costs by 5% to 15%, while deadbolt locks, security cameras, and impact-resistant windows qualify for discounts at most carriers. Huntington’s coastal location and older home stock make these upgrades especially valuable since insurers view them as genuine risk reduction. You don’t need to renovate your entire home-focus on entry points and visible deterrents that insurers specifically recognize on their discount schedules.
Protect Your Claims History
Your claims history matters more than most homeowners realize. A single water damage or theft claim can increase your premiums by 10% to 25% for three to five years, making it critical to address problems before they escalate into claims. Roof leaks, foundation cracks, and plumbing issues cost far less to fix upfront than to claim later. Insurers also reward longevity-staying with the same carrier for three or more years typically qualifies you for loyalty discounts ranging from 5% to 10%.
Why Independent Agents Outperform Online Platforms
An independent agent reviews your current coverage annually, identifies new discounts you’ve become eligible for, and shops your policy across multiple carriers every few years to ensure you’re not overpaying. This hands-on approach catches gaps and savings opportunities that static online platforms simply miss. As a third-generation, family-owned independent insurance agency in Huntington, we act as your advocate throughout the entire process-not just at the point of sale.
These cost-reduction strategies work best when paired with a thorough review of what your coverage actually protects. Many Huntington homeowners discover they’re either underinsured or carrying unnecessary coverage, which brings us to the coverage gaps that matter most.
Coverage Gaps That Cost Huntington Homeowners Thousands
Underinsuring Your Property Value
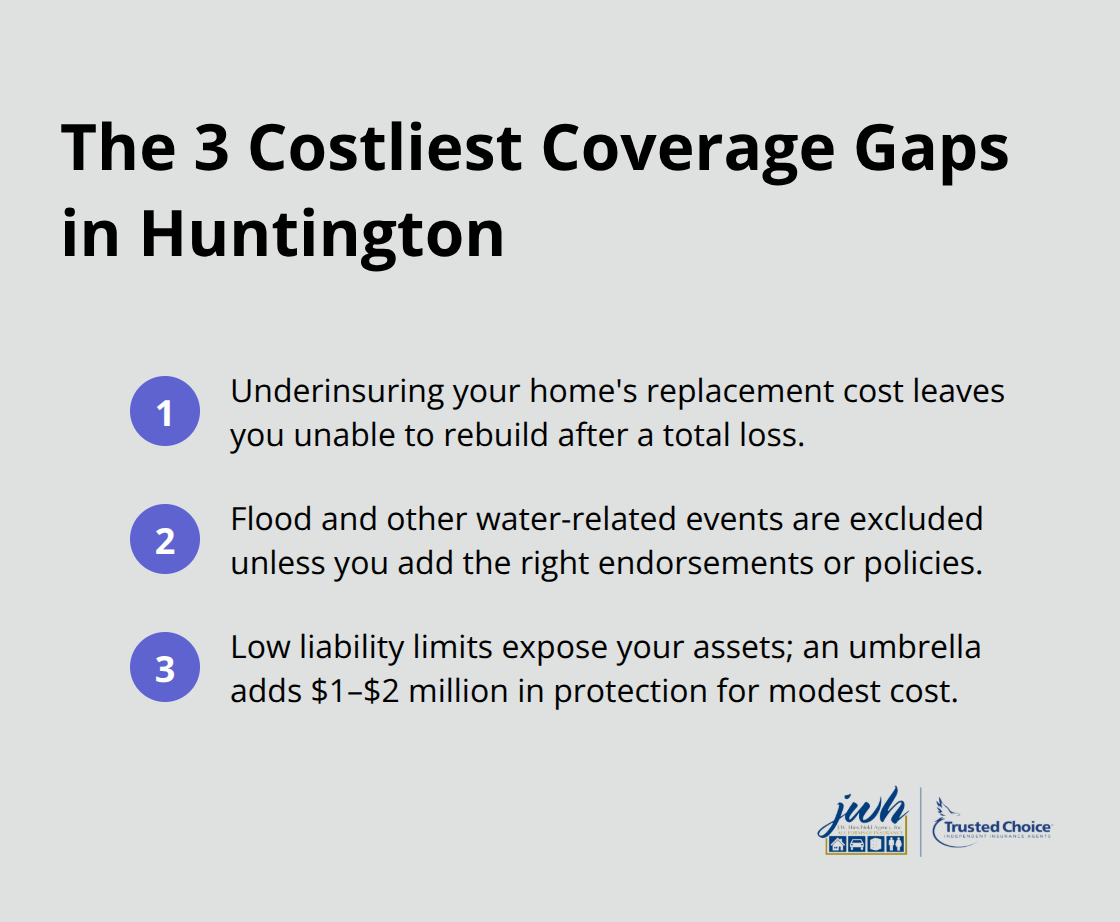
Most Huntington homeowners severely undervalue their property or ignore coverage types that matter most when disaster strikes. The National Association of Insurance Commissioners found that nearly 30% of homeowners are underinsured by at least 20%, meaning they cannot fully rebuild after a total loss. Huntington’s combination of older homes, coastal exposure, and rising construction costs makes this gap particularly dangerous. A home worth $450,000 to rebuild often carries only $350,000 in coverage because homeowners base limits on purchase price rather than replacement cost. Construction costs have risen significantly, and labor inflation continues to push rebuilding expenses higher. That gap becomes catastrophic when you factor in material shortages and current market rates. An independent agent conducts detailed home inventories and works with carriers to set replacement cost values that actually reflect what rebuilding costs today, not what your home sold for five years ago.
Water Damage and Flood Coverage Blind Spots
Water damage represents the second massive blind spot, and standard homeowners policies exclude it entirely. Standard policies exclude flood damage completely, yet the National Flood Insurance Program reports that average flood claims in New York exceed $30,000, with some reaching $70,000 or more. Huntington’s location near Long Island Sound and its aging stormwater systems create genuine flood risk that most homeowners dismiss. Separate flood insurance through the National Flood Insurance Program or private carriers costs between $400 and $1,200 annually depending on risk level, but skipping it leaves you exposed to losses that savings accounts simply cannot cover.
Beyond flood, sump pump failures, sewer backups, and water seepage from heavy rain often fall into coverage gaps because homeowners assume standard policies handle water intrusion. These situations cause significant damage but fall outside typical homeowners protection. A single water event can cost $10,000 to $50,000 in repairs, making targeted water coverage a practical investment rather than an optional add-on.
Liability Protection for High-Risk Situations
The third critical gap involves liability protection for situations that exceed standard policy limits. A serious injury on your property, a dog bite that requires multiple surgeries, or an accident you’re found responsible for can generate medical bills and legal judgments reaching $500,000 or more. Standard homeowners policies typically cap liability at $100,000 to $300,000, which leaves substantial exposure for Huntington families with assets to protect. Umbrella policies add $1 million to $2 million in liability coverage for just $150 to $300 annually, yet most homeowners never purchase them because online platforms don’t actively recommend what they don’t sell.
These three gaps appear repeatedly in claims conversations and represent the difference between financial recovery and financial ruin. An independent agent identifies these exposures during a thorough policy review and recommends solutions tailored to your specific situation and assets. This personalized approach is exactly what separates working with a local agent from relying on generic online quotes.
Why Independent Agents Win Against Online Quotes
Multiple Carriers, Better Rates
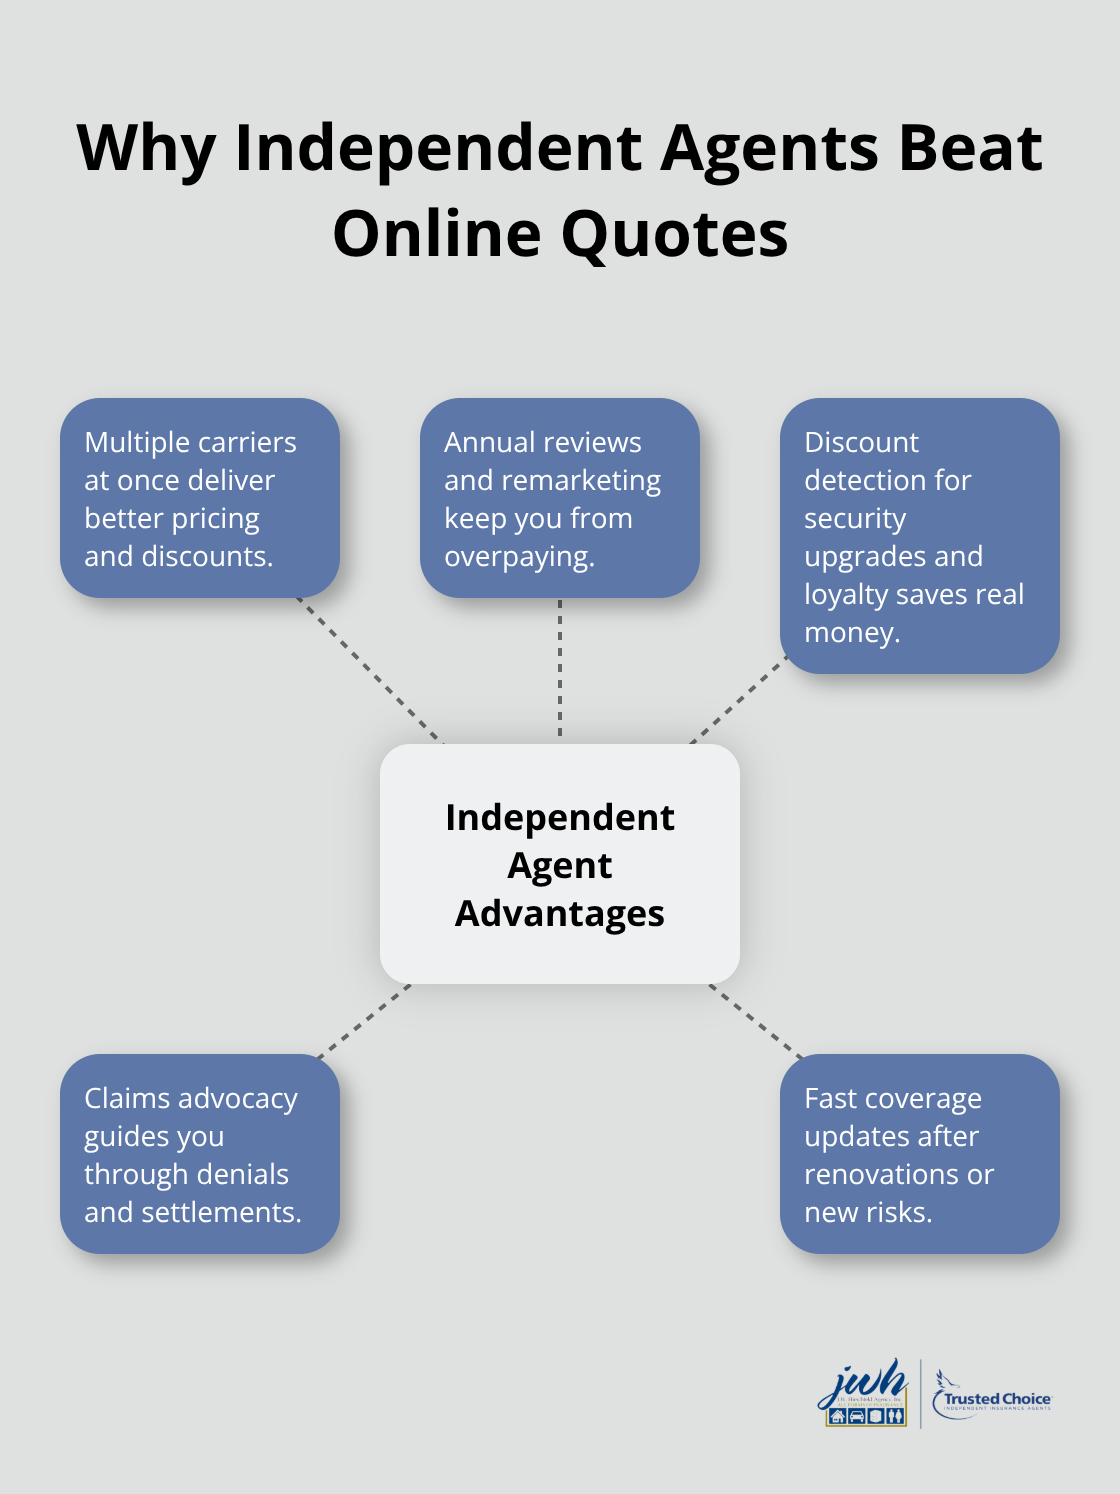
Online quote platforms operate on a fundamentally flawed model for homeowners seeking real protection. They show you rates from one or two carriers at a time, forcing you to run quotes across five or six different websites to compare options-a process that takes hours and still leaves you guessing whether you’ve found the best deal. Independent agents represent multiple top carriers simultaneously, which means they access pricing and discounts that fragmented online shopping simply cannot match. A homeowner bundling auto, home, and umbrella coverage might qualify for significant savings through one carrier but an additional discount through another-savings that vanish when you’re locked into whichever online platform happened to show the lowest initial quote.
Independent agents also catch pricing errors and missed discounts that automated systems overlook. An online quote might show your home at replacement cost of $350,000 when actual rebuilding expenses reach $450,000, or fail to apply available discounts for security features you already installed. An agent reviews your full situation, identifies what coverage gaps matter most for your specific assets and risk profile, then matches you with carriers that reward the exact details of your home and lifestyle.
Personalized Coverage That Fits Your Home
Online platforms treat every home as identical, applying generic coverage limits that rarely match your actual situation. An independent agent conducts detailed home inventories and works with carriers to set replacement cost values that reflect what rebuilding costs today, not what your home sold for five years ago. This personalized approach catches exposures that automated systems miss entirely.
An agent also identifies which discounts apply to your specific circumstances. You installed security cameras last year? An agent applies that discount across multiple carriers to find the one offering the largest reduction. You added a pool or renovated your kitchen? An agent updates your coverage in minutes and identifies new discounts you’ve become eligible for based on home improvements.
Real Support When Claims Happen
Claims and policy changes reveal the real divide between online platforms and independent representation. When water damage floods your basement at 2 AM, an online quote tool cannot help you navigate coverage questions, coordinate with adjusters, or push back on coverage denials. An independent agent acts as your advocate throughout the entire claims process, understanding your policy language and ensuring you receive the settlement you paid for.
Policy changes create similar friction with online platforms. If you add a pool or renovate your kitchen, online platforms require you to manually restart the entire quoting process across multiple sites. An independent agent updates your coverage in minutes and identifies new discounts you’ve become eligible for based on home improvements. These details become part of ongoing service rather than separate transactions.
The Real Cost Difference
The annual cost difference between working with an independent agent and relying on online quotes varies based on your specific situation and coverage needs. The protection and peace of mind during actual claims situations, however, proves far more valuable than any premium comparison. An independent agent manages your coverage as an ongoing relationship, not as a one-time transaction that ends the moment you purchase a policy.
Final Thoughts
Huntington homeowners who overpay for coverage or carry dangerous gaps typically share one thing in common: they relied on online quotes instead of working with someone who understands their specific situation. Smart Huntington home insurance tips work best when paired with a thorough policy review from someone who represents multiple carriers and acts as your advocate, not just a transaction processor. Three concrete actions separate smart decisions from costly mistakes: bundle your policies across multiple carriers to find the combination that saves you the most money, close the coverage gaps that matter most (replacement cost matching actual rebuilding expenses, flood coverage if you’re in a risk zone, and umbrella protection if you have assets to defend), and invest in security upgrades that insurers specifically reward with discounts.
Working with a local independent agent saves you money in ways that online platforms simply cannot match. An agent shops your coverage across multiple top carriers simultaneously, identifies discounts you’ve become eligible for, and catches underinsurance problems before they become catastrophic losses. When claims happen, an independent agent advocates for you instead of leaving you to navigate policy language and adjuster negotiations alone, and these services cost nothing extra because independent agents earn commissions from carriers, just like online platforms do.
Your next step is straightforward: schedule a policy review with JW Hirschfeld Agency, Inc., a third-generation, family-owned independent agency in Huntington representing multiple top carriers. A detailed review takes less than an hour and identifies exactly where you’re overpaying, underinsured, or missing discounts. That conversation costs nothing and often reveals thousands in annual savings or critical coverage gaps you didn’t know existed.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.