
Workers compensation premium factors aren’t random. Insurance companies use specific formulas based on your claims history, payroll, and industry risk to calculate what you’ll pay.
At JW Hirschfeld Agency, Inc., we help Huntington business owners understand exactly why their rates are set the way they are. The good news is that knowing these factors gives you leverage to negotiate better coverage and pricing.
How Insurance Companies Calculate Workers Compensation Premiums
Experience Modification Rate and Claims History
Insurance companies don’t pull workers compensation rates from thin air-they calculate them using three interconnected factors that directly impact what you pay. Your experience modification rate, or EMR, sits at the center of this calculation.
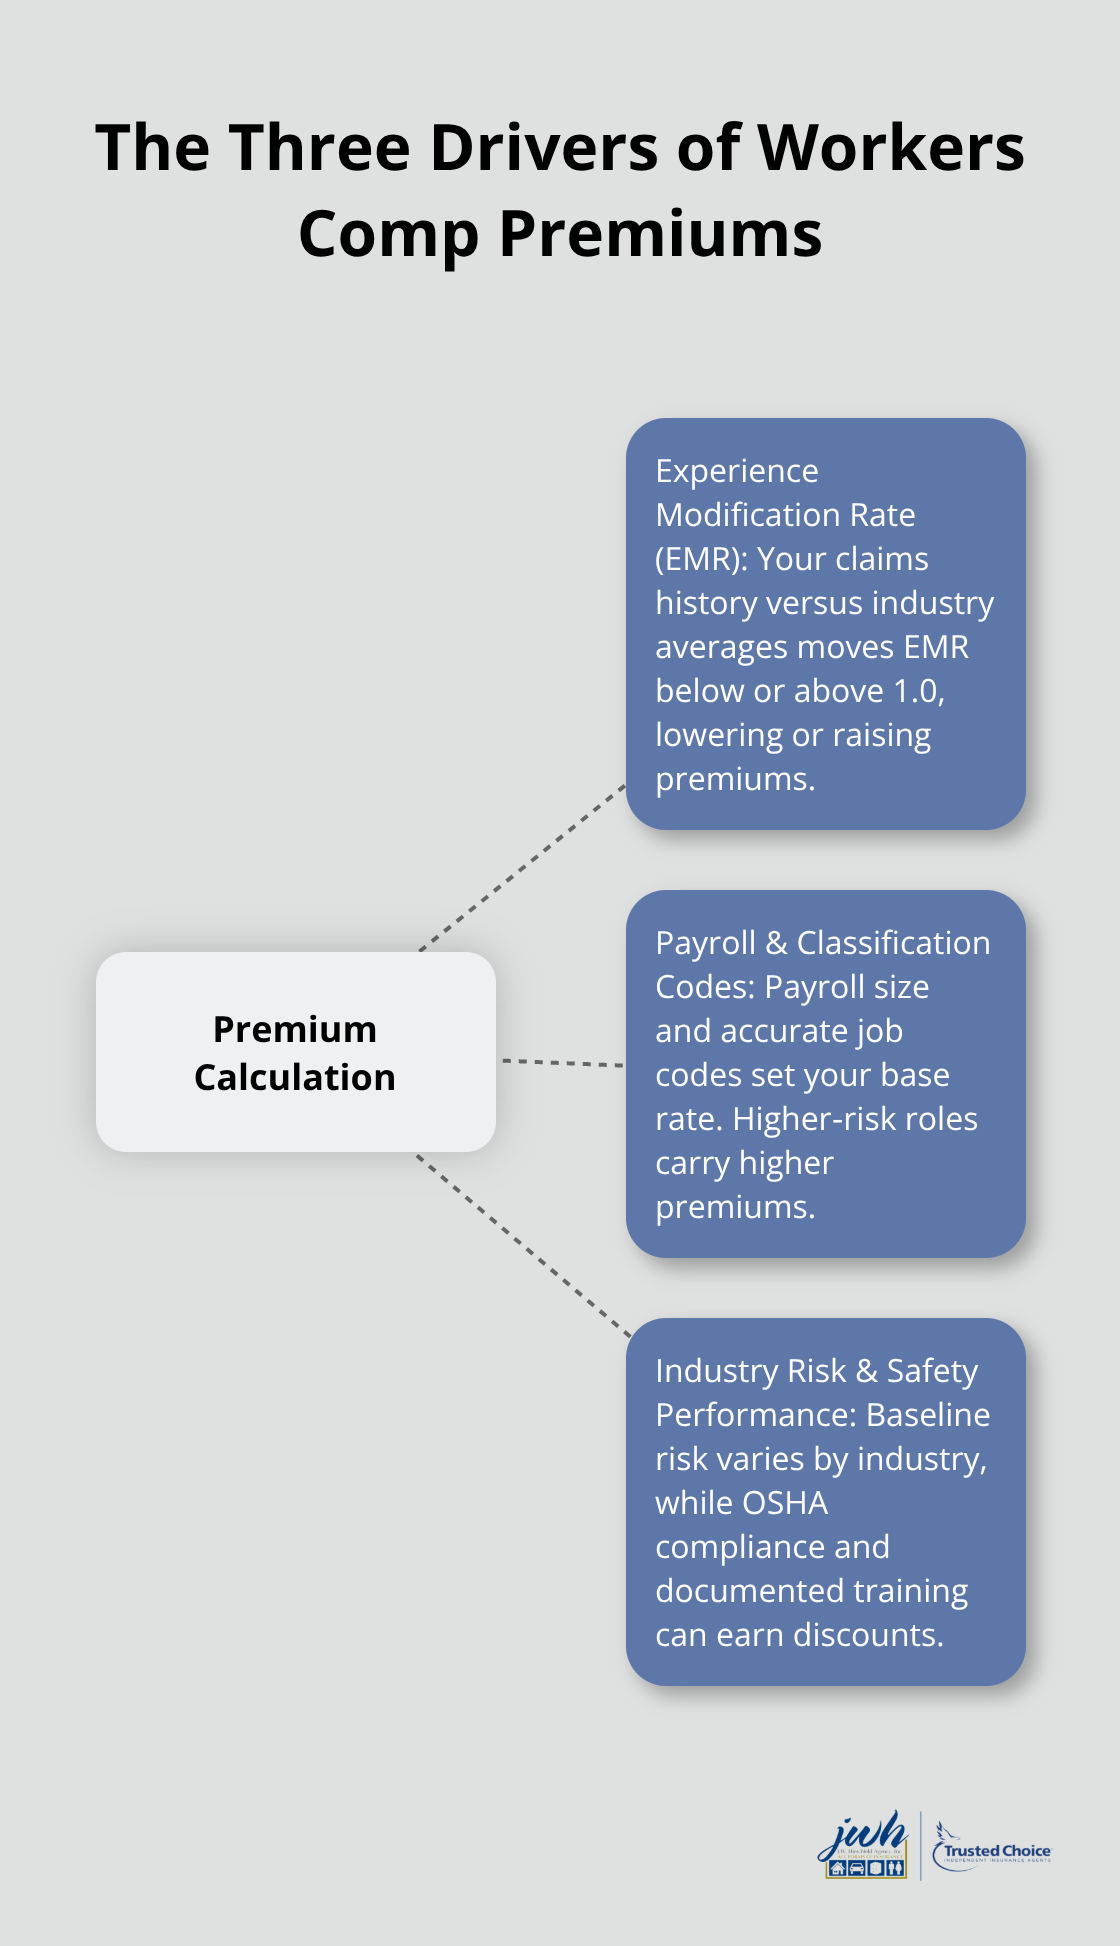
If your business files fewer claims than average for your industry, your EMR drops below 1.0, which means you pay less than the standard rate. Conversely, businesses with above-average claims history see EMRs above 1.0 and pay higher premiums than baseline.
The National Council on Compensation Insurance reports that this single factor can swing your annual premium by thousands of dollars, making your claims history one of the most controllable levers you have. A business owner in Huntington with a clean five-year record will see dramatically different pricing than one with multiple claims, even if both operate in the same industry.
Payroll and Job Classification Codes
Your payroll and job classification codes form the second pillar of premium calculation. Insurance carriers assign classification codes based on the specific duties your employees perform-a code for office staff differs significantly from a code for warehouse workers or electricians. The Bureau of Labor Statistics tracks injury rates by classification, and some codes carry inherent risk premiums because workers in those roles file claims at higher rates.
If you misclassify employees into lower-risk categories to save money, you set yourself up for audits and premium adjustments that can exceed your initial savings. Auditors scrutinize payroll records carefully, and carriers impose penalties when they discover inaccurate classifications.
Industry Risk and Safety Performance
Industry risk assessment and your actual safety record complete the equation. A roofing contractor in Huntington faces substantially higher baseline rates than a marketing firm because the construction industry reports injury rates five times higher than professional services. However, if your roofing company implements fall protection systems, maintains OSHA compliance, and documents safety training, insurers may offer discounts on top of your base rate.
Your location matters too-Huntington’s specific regulatory environment and local loss data influence rates. An independent agent can shop multiple carriers to find the best pricing for your particular risk profile rather than accepting the first quote you receive, which is where local expertise makes a real difference in what you ultimately pay.
Key Factors That Affect Your Premium in Huntington
Business Size and Employee Count
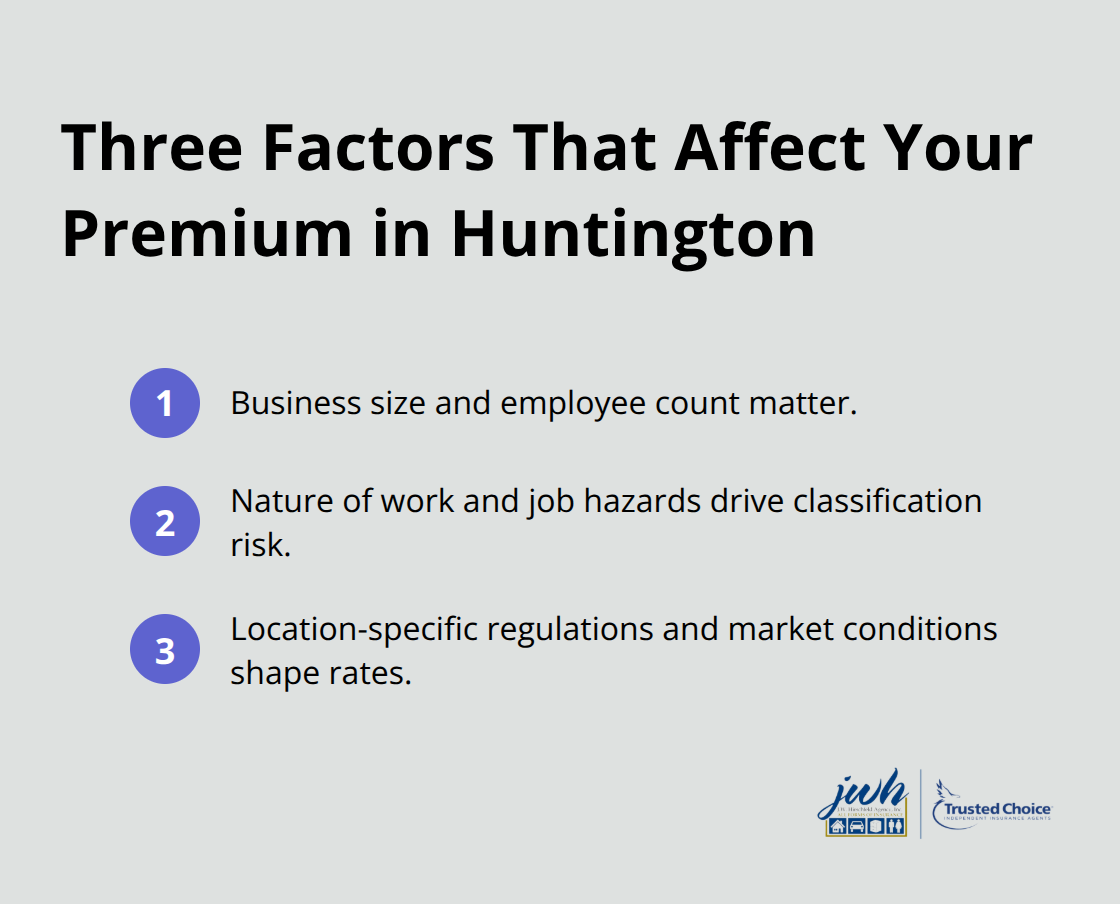
Your business size creates the mathematical foundation for your premium. A Huntington contractor with five employees pays fundamentally different rates than one with fifty, not just because payroll is higher, but because premium structures reward larger payrolls with modest discounts per employee. The National Council on Compensation Insurance data shows that businesses with ten to twenty-five employees often occupy an awkward middle ground where they’ve lost small-business pricing advantages but haven’t yet reached the volume discounts available to larger operations.
Growing from five to fifteen employees shifts your per-employee premium downward slightly, though your total premium obviously increases with payroll. The inverse happens when you contract staff-reducing headcount can lower your overall premium, but carriers recalculate your experience modification rate based on the new payroll base, sometimes resulting in rate increases if your claims history now appears worse proportionally.
Nature of Work and Job Hazards
The specific work your employees perform matters far more than most business owners realize. Construction trades in Huntington face significantly higher premiums than office-based work because electricians, roofers, and heavy equipment operators file claims at dramatically higher rates. According to OSHA injury statistics, approximately 5,000–5,500 workers are fatally injured in the USA each year. A single classification change-moving an employee from general labor to skilled trades-can trigger substantial premium adjustments that carriers calculate based on industry loss data.
Location-Specific Regulations and Market Conditions
Huntington’s local market conditions and New York State’s regulatory framework create additional premium layers that shape what you ultimately pay. New York maintains strict workers compensation rules, and Huntington-based businesses benefit from some of the state’s most competitive carrier presence, meaning rate shopping here produces genuine savings compared to other regions. Location-specific factors like Huntington’s proximity to maritime industries, construction activity levels, and local labor costs all influence how carriers price your premium.
Getting multiple quotes from different insurers reveals these variations quickly-something a single-carrier agent cannot offer. An independent agent representing multiple top carriers understands which insurers price aggressively for your specific classification in Huntington and which ones routinely overprice local risks. This knowledge directly translates to lower premiums for your business.
Understanding these three factors positions you to make informed decisions about your coverage, but the real advantage comes from working with someone who shops multiple carriers on your behalf. That’s where independent agents create measurable value for Huntington business owners.
Why Independent Agents Deliver Lower Premiums
Access to Multiple Carriers Means Real Price Differences
A single-carrier agent locks you into whatever price they quote, regardless of whether better options exist elsewhere. Independent agents represent multiple top carriers simultaneously, which allows them to compare quotes from five, ten, or sometimes fifteen different insurers for your exact risk profile in Huntington. If your current agent represents only one or two carriers, you’re almost certainly overpaying.
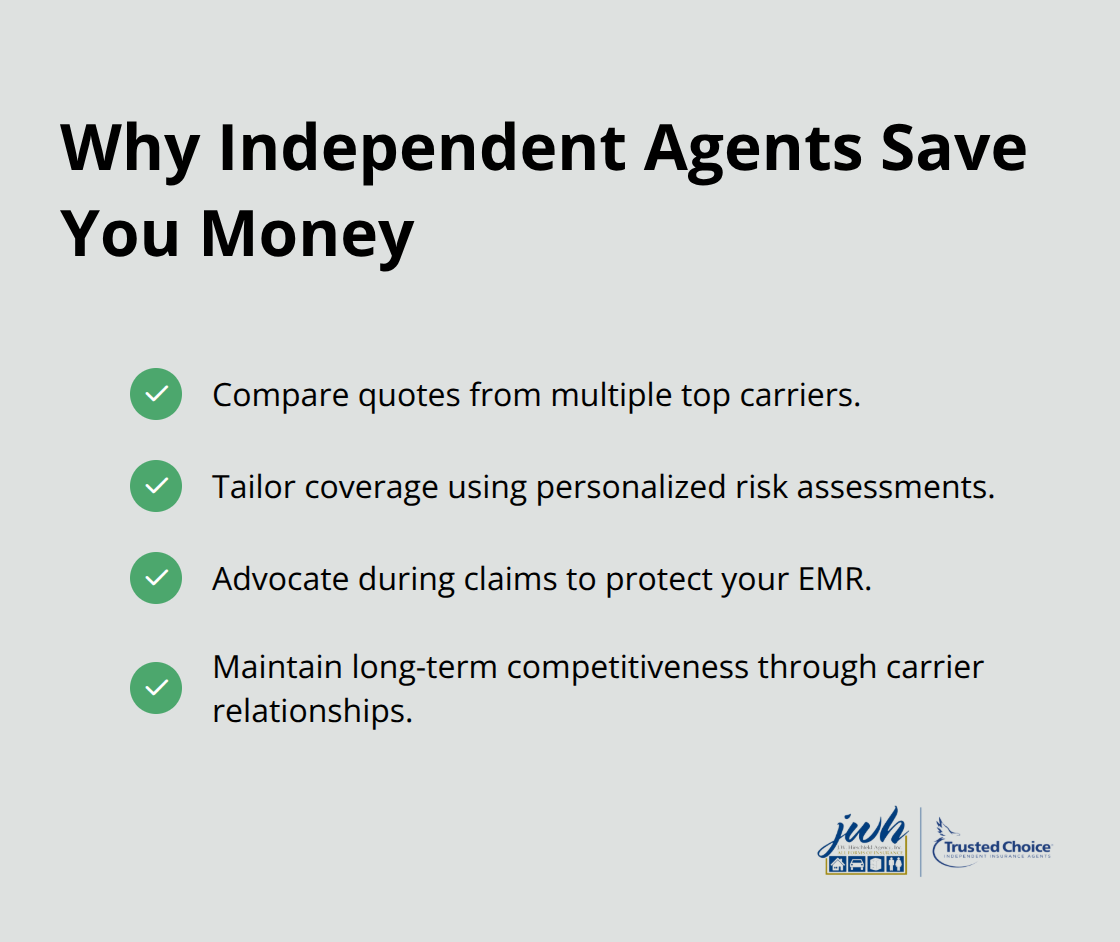
An independent agent can show you side-by-side comparisons from carriers that price aggressively for your specific industry and classification code in Huntington, then negotiate additional discounts based on your safety record and claims history. Some carriers offer discounts for businesses maintaining OSHA compliance documentation or completing safety training programs-discounts that single-carrier agents may not even know exist because they lack access to those insurers’ full rate sheets.
Personalized Risk Assessment Reveals Hidden Savings
Independent agents conduct personalized risk assessments that often reveal premium reduction opportunities you’d miss alone. A Huntington construction company might qualify for equipment rental coverage under their policy at no additional cost, or they might reduce premiums by reclassifying certain administrative employees from field worker codes to office codes based on their actual duties. These adjustments require someone who understands both your operations and how different carriers evaluate risk-something a captive agent simply cannot provide.
Advocacy That Protects Your Future Rates
During claims, independent agents act as your advocate with the carrier, ensuring adjusters process your claim fairly and quickly rather than leaving you to navigate the process solo. This advocacy directly protects your experience modification rate, since faster claims resolution and proper documentation prevent disputes that inflate future premiums. An independent broker with deep carrier relationships can often expedite claim handling and resolve disputes before they damage your long-term pricing.
Long-Term Competitive Positioning
Working with an independent agent who understands Huntington’s market and carries relationships with multiple carriers positions your business to secure better rates during renewal cycles, access emerging discounts before competitors discover them, and maintain competitive pricing even as your claims history evolves. As a third-generation, family-owned independent insurance agency in Huntington, JW Hirschfeld Agency, Inc. brings nearly a century of local market knowledge and established carrier relationships that translate directly into better pricing for your workers compensation coverage.
Final Thoughts
Workers compensation premium factors ultimately determine what you pay, but understanding these factors means nothing without action. A single-carrier agent quotes you one price and stops there, while an independent agent shops multiple carriers simultaneously to find which insurers price aggressively for your specific classification in Huntington. The difference between these approaches often amounts to thousands of dollars annually, and that gap widens each year you remain with the wrong carrier.
Independent agents also advocate for you during claims, which protects your experience modification rate for future years. When adjusters process your claim fairly and quickly, disputes don’t inflate your premiums down the road-this hands-on support during difficult moments separates independent brokers from captive agents who lack the carrier relationships needed to expedite resolution. Local independent agencies understand Huntington’s specific market conditions and maintain relationships with top carriers that translate directly into better pricing for your business.
Contact JW Hirschfeld Agency, Inc. to discuss your workers compensation coverage and discover how independent representation translates into better rates for your Huntington business. We represent multiple carriers simultaneously, which means we can show you genuine rate comparisons rather than a single quote. Our personalized risk assessments reveal premium reduction opportunities you might miss alone.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.